Independent writing on tax-smart planning, mortgage strategy, and retirement building. For Canadian professionals who want the whole picture, not just a piece of it.
Why The GTA's $671,076 Price Gap Between Condos And Houses Means Falling Prices Won't Help You Trade Up
Yara bought her one-bedroom condo in Scarborough in August 2024 for $590,000. She put down 10%, got an insured mortgage at 4.79%, and locked in monthly payments of $3,140. Two years later, condos in her building are selling for $565,000. She's lost equity. A detached semi in the same neighbourhood, walking distance from her building, just listed for $1.26 million. Even if that semi drops 10% over the next year, it will still cost $1.13 million. Yara would need to come up with roughly $800,000 more than what she could get for her condo today. The gap is structural and the condo falling in value does nothing to close it.
The $671,076 Chasm
The Toronto Regional Real Estate Board reported an average resale price of $993,410 for the Greater Toronto Area in August 2026. Break that down by property type and the picture changes. The average condo sold for $617,593. The average detached home hit $1,288,669. The spread between them is $671,076, more than the total cost of the condo itself.
That gap is what first-time buyers run into when they try to "move up." The question is not whether to save a bit more or wait for rates to drop, but whether to finance the equivalent of two condos to make the jump to one house.
Why Falling Prices Don't Shrink the Gap
Market corrections do not compress the spread proportionally. Condos and detached homes move in different directions because they respond to different forces. The condo market in downtown Toronto is oversupplied. Investors who bought pre-construction units in 2021 are now trying to exit, pushing inventory up and prices down. Detached homes in the 905 suburbs remain scarce. Sellers with equity can afford to wait. They are not forced to drop prices at the same rate.
Run the arithmetic on a 10% correction across both categories. A $618,000 condo falls to $556,200. A $1.29 million detached home falls to $1.16 million. The gap narrows from $671,076 to $603,800. The buyer who could not bridge $671k cannot bridge $604k either, even though the math is cleaner.
The 20% Down Payment Wall
The affordability problem centers on the regulatory threshold. In Canada, any home over $1 million requires a minimum 20% down payment. No exceptions. For a detached home at the August average of $1,288,669, that is $257,734 up front. A $618,000 condo requires roughly $37,000 down if the buyer qualifies for an insured mortgage. This difference is a step-function into a different debt service and liquidity tier, not a mere incremental change.
Most GTA households cannot accumulate $257,734 in cash while also carrying a mortgage, paying condo fees, and covering cost-of-living increases. The borrowing power required to service a $1.03 million mortgage (80% of $1.29M) is also well beyond what a household making $92,000, roughly the median family income in the GTA, can support under the current stress test.
What Actually Bridges the Gap
Housing stock is the missing piece. The GTA has a shortage of townhomes, stacked townhomes, and semis priced between $750,000 and $950,000. These are the properties that historically allowed condo owners to trade up without needing to double their financial capacity overnight. Developers stopped building them because land costs in the GTA make it more profitable to build either high-density condos or detached homes on large suburban lots. The middle is gone.
Until supply fills in that range, or until household incomes rise enough to support the $1M+ threshold, the property ladder stays broken. Falling prices might make each rung cheaper. They do not make the rungs any closer together.


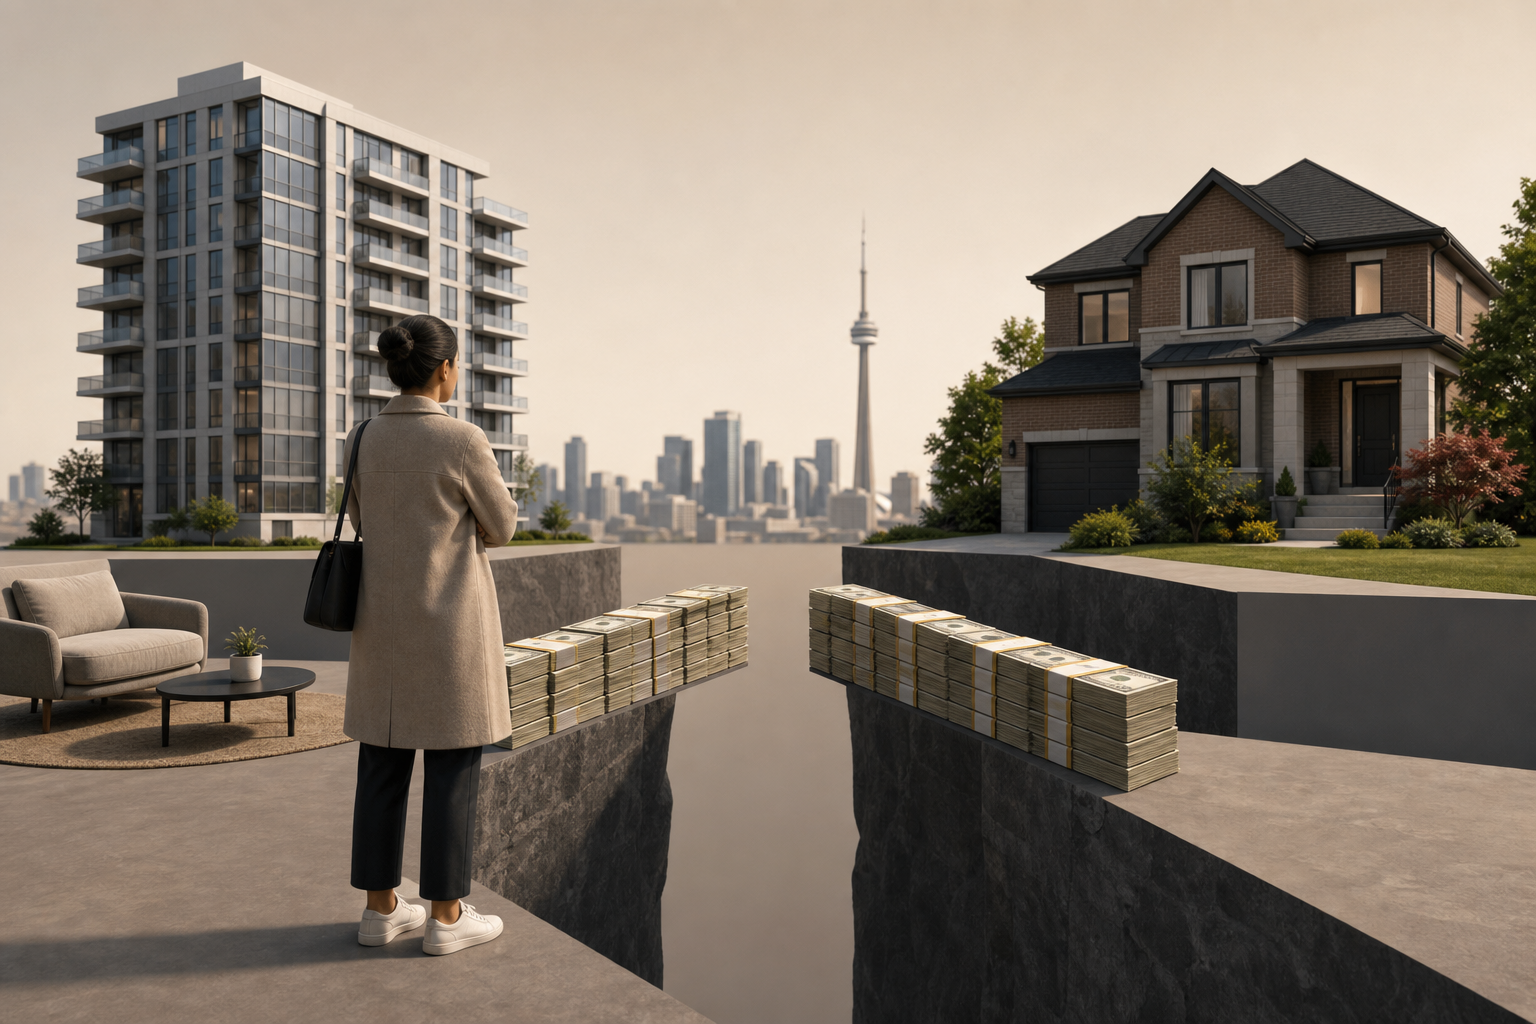

Yara bought her one-bedroom condo in Scarborough in August 2024 for $590,000. She put down 10%, got an insured mortgage at 4.79%, and locked in monthly payments of $3,140. Two years later, condos in her building are selling for $565,000. She's lost equity. A detached semi in the same neighbourhood, walking distance from her building, just listed for $1.26 million. Even if that semi drops 10% over the next year, it will still cost $1.13 million. Yara would need to come up with roughly $800,000 more than what she could get for her condo today. The gap is structural and the condo falling in value does nothing to close it.
The $671,076 Chasm
The Toronto Regional Real Estate Board reported an average resale price of $993,410 for the Greater Toronto Area in August 2026. Break that down by property type and the picture changes. The average condo sold for $617,593. The average detached home hit $1,288,669. The spread between them is $671,076, more than the total cost of the condo itself.
That gap is what first-time buyers run into when they try to "move up." The question is not whether to save a bit more or wait for rates to drop, but whether to finance the equivalent of two condos to make the jump to one house.
Why Falling Prices Don't Shrink the Gap
Market corrections do not compress the spread proportionally. Condos and detached homes move in different directions because they respond to different forces. The condo market in downtown Toronto is oversupplied. Investors who bought pre-construction units in 2021 are now trying to exit, pushing inventory up and prices down. Detached homes in the 905 suburbs remain scarce. Sellers with equity can afford to wait. They are not forced to drop prices at the same rate.
Run the arithmetic on a 10% correction across both categories. A $618,000 condo falls to $556,200. A $1.29 million detached home falls to $1.16 million. The gap narrows from $671,076 to $603,800. The buyer who could not bridge $671k cannot bridge $604k either, even though the math is cleaner.
The 20% Down Payment Wall
The affordability problem centers on the regulatory threshold. In Canada, any home over $1 million requires a minimum 20% down payment. No exceptions. For a detached home at the August average of $1,288,669, that is $257,734 up front. A $618,000 condo requires roughly $37,000 down if the buyer qualifies for an insured mortgage. This difference is a step-function into a different debt service and liquidity tier, not a mere incremental change.
Most GTA households cannot accumulate $257,734 in cash while also carrying a mortgage, paying condo fees, and covering cost-of-living increases. The borrowing power required to service a $1.03 million mortgage (80% of $1.29M) is also well beyond what a household making $92,000, roughly the median family income in the GTA, can support under the current stress test.
What Actually Bridges the Gap
Housing stock is the missing piece. The GTA has a shortage of townhomes, stacked townhomes, and semis priced between $750,000 and $950,000. These are the properties that historically allowed condo owners to trade up without needing to double their financial capacity overnight. Developers stopped building them because land costs in the GTA make it more profitable to build either high-density condos or detached homes on large suburban lots. The middle is gone.
Until supply fills in that range, or until household incomes rise enough to support the $1M+ threshold, the property ladder stays broken. Falling prices might make each rung cheaper. They do not make the rungs any closer together.
Read Next
Three CREA Downgrades in One Year Should Retire the 'Temporary Dip' Theory
Mortgage-Free in Retirement? The 4 Costs Your Home Still Charges You
Higher Rates, Softer Hiring: What 2026's Housing Shift Means for Your Equity
The Toronto Penthouse Premium: What Holds Value and What Is Just Status