Independent writing on tax-smart planning, mortgage strategy, and retirement building. For Canadian professionals who want the whole picture, not just a piece of it.
Toronto's Rental Relief Is Temporary: Why 60% Fewer Condo Sales in 2025 Will Tighten Supply by 2027
A two-bedroom condo in Liberty Village recently traded hands at market rates in the $2,000–$3,000 range, with landlords offering concessions including free rent months as occupancy pressure persists. For Toronto renters, this is the market finally delivering relief after years of being squeezed. The problem is what happens when the units being built right now are the last ones available.
The pipeline has already emptied
Greater Toronto Area new condo sales collapsed in 2024 and 2025, falling 78% below the 10-year average in 2024 and 91% below in 2025, according to Urbanation. That isn't a slump. That is the channel shutting off. Pre-construction condo sales hit decade-level lows in 2025, with quarterly declines exceeding 88% below the ten-year average. High interest rates pushed carrying costs into deep negative cash flow territory for individual investors, the group of individual investors who have historically been significant suppliers of Toronto's rental stock by purchasing units and renting them out. Those investors have stopped buying. Projects that would have launched in 2024 and 2025 got shelved or cancelled outright, with several thousand planned units put on indefinite hold.
Toronto's condo development lag — from sale to completion — stretches several years. The units completing now, the ones flooding the rental market and driving down rents, were sold in 2019 through 2021, back when pre-construction was a feeding frenzy. That wave is landing all at once. Behind it: almost nothing.
Why the investor retreat matters structurally
Toronto does not have enough purpose-built rental construction to meet demand without the individual investor acting as a de facto rental developer. A substantial share of the city's condo stock is investor-owned and rented out. When those buyers exit the market, the long-term rental pool shrinks, even if today's supply looks abundant. The rental relief renters are experiencing in 2025 and 2026 is a temporary oversupply created by completions that were set in motion half a decade ago.
The current sweetspot has an expiration date. Once the market digests the last of the 2019, 2021 boom units, the supply cliff hits. The supply cliff will arrive when units from today's collapsed sales would have been finishing — a point several years out, likely in the late 2020s. There is nothing behind them in the pipeline to meet population growth or replacement demand.
The rent control trap nobody talks about
Ontario's Residential Tenancies Act exempts buildings first occupied after November 15, 2018 from provincial rent increase guidelines. Most new condos fall into that category. A tenant moving into a newly completed unit today to lock in a $2,600 rent is not protected from a market-rate reset when their lease renews. If supply tightens sharply in 2027, landlords can raise rents to whatever the market will bear. The tenant who thought they were securing long-term affordability by jumping into the current market may face a 20% or 30% increase two years out, with no legal cap to soften it.
That dynamic does not exist for tenants in older buildings covered by rent control, where annual increases are capped at 2.5% for 2025 and 2.1% for 2026. The post-2018 stock, which makes up most of the rental inventory added in the last five years, offers no such protection.
The federal and institutional shift
The federal government introduced GST exemptions for new purpose-built rental projects, part of efforts to encourage apartment development. Institutional developers are starting to move into the space, but their projects take years to deliver and often target different price points than the individual investor condos that have dominated supply. If the Bank of Canada continues lowering rates through 2026, the pre-construction market could recover faster than current sales data suggests, shortening the supply gap. But that is speculative. The hard number is the 60% sales collapse that has already happened.
Renters have leverage now. The question is whether they understand it expires the moment the current completion wave runs out.


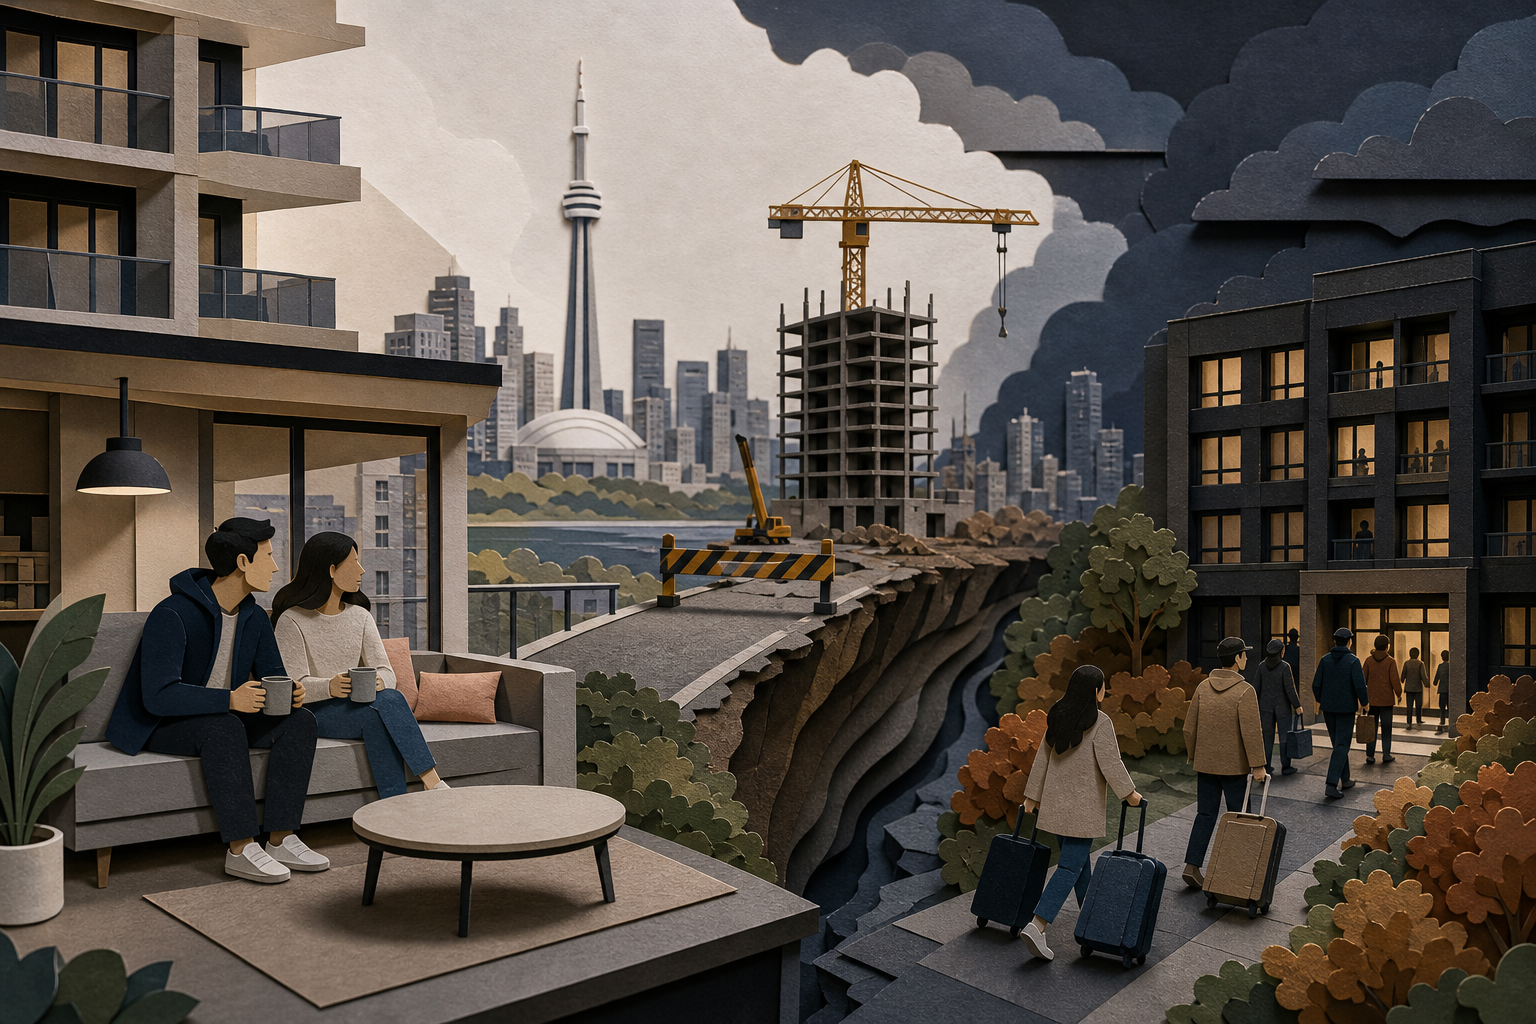

A two-bedroom condo in Liberty Village recently traded hands at market rates in the $2,000–$3,000 range, with landlords offering concessions including free rent months as occupancy pressure persists. For Toronto renters, this is the market finally delivering relief after years of being squeezed. The problem is what happens when the units being built right now are the last ones available.
The pipeline has already emptied
Greater Toronto Area new condo sales collapsed in 2024 and 2025, falling 78% below the 10-year average in 2024 and 91% below in 2025, according to Urbanation. That isn't a slump. That is the channel shutting off. Pre-construction condo sales hit decade-level lows in 2025, with quarterly declines exceeding 88% below the ten-year average. High interest rates pushed carrying costs into deep negative cash flow territory for individual investors, the group of individual investors who have historically been significant suppliers of Toronto's rental stock by purchasing units and renting them out. Those investors have stopped buying. Projects that would have launched in 2024 and 2025 got shelved or cancelled outright, with several thousand planned units put on indefinite hold.
Toronto's condo development lag — from sale to completion — stretches several years. The units completing now, the ones flooding the rental market and driving down rents, were sold in 2019 through 2021, back when pre-construction was a feeding frenzy. That wave is landing all at once. Behind it: almost nothing.
Why the investor retreat matters structurally
Toronto does not have enough purpose-built rental construction to meet demand without the individual investor acting as a de facto rental developer. A substantial share of the city's condo stock is investor-owned and rented out. When those buyers exit the market, the long-term rental pool shrinks, even if today's supply looks abundant. The rental relief renters are experiencing in 2025 and 2026 is a temporary oversupply created by completions that were set in motion half a decade ago.
The current sweetspot has an expiration date. Once the market digests the last of the 2019, 2021 boom units, the supply cliff hits. The supply cliff will arrive when units from today's collapsed sales would have been finishing — a point several years out, likely in the late 2020s. There is nothing behind them in the pipeline to meet population growth or replacement demand.
The rent control trap nobody talks about
Ontario's Residential Tenancies Act exempts buildings first occupied after November 15, 2018 from provincial rent increase guidelines. Most new condos fall into that category. A tenant moving into a newly completed unit today to lock in a $2,600 rent is not protected from a market-rate reset when their lease renews. If supply tightens sharply in 2027, landlords can raise rents to whatever the market will bear. The tenant who thought they were securing long-term affordability by jumping into the current market may face a 20% or 30% increase two years out, with no legal cap to soften it.
That dynamic does not exist for tenants in older buildings covered by rent control, where annual increases are capped at 2.5% for 2025 and 2.1% for 2026. The post-2018 stock, which makes up most of the rental inventory added in the last five years, offers no such protection.
The federal and institutional shift
The federal government introduced GST exemptions for new purpose-built rental projects, part of efforts to encourage apartment development. Institutional developers are starting to move into the space, but their projects take years to deliver and often target different price points than the individual investor condos that have dominated supply. If the Bank of Canada continues lowering rates through 2026, the pre-construction market could recover faster than current sales data suggests, shortening the supply gap. But that is speculative. The hard number is the 60% sales collapse that has already happened.
Renters have leverage now. The question is whether they understand it expires the moment the current completion wave runs out.
Sources
Read Next
Ottawa Already Holds the Income Data That Could Curb Mortgage Fraud
Ferries, Septic and Storm Insurance: What a Vancouver Island Cottage Really Costs Yearly
Six Bulk Buyers Took 339 Toronto Condos at 40% Off: Their Risk Checklist
If Cleveland-Cliffs Can Break Its Stelco Pledges, Every Foreign Buyer Will