Independent writing on tax-smart planning, mortgage strategy, and retirement building. For Canadian professionals who want the whole picture, not just a piece of it.
Naming Your US-Based Child on a RRIF Can Mean Two Tax Bills
If you have a RRIF and an adult child south of the border, pull out your own designation and look at it. The plan you made assumed one tax system. Your child lives under two, and the money can be taxed by both before it settles in their account. I teach this as one of the quieter estate risks I see, because nothing about it feels risky until the estate is being settled.
Why the RRIF rollover disappears when your child lives in the US
Most people's sense that RRIFs pass smoothly comes from the spousal case. Leave the account to a spouse and Canada lets it roll over, tax-deferred. That rollover is reserved for spouses, so a US-based child, an adult non-spouse, doesn't get it.
When there's no surviving spouse named, typically 100% of the RRIF balance is added to the deceased's final Canadian return. As an illustration, a $500,000 RRIF stacked on top of a year's other income pushes much of it into Manitoba's top bracket. On a lump sum paid to a non-resident, the financial institution may also apply Canada's standard 25% non-resident withholding. The 15% treaty rate is meant for periodic payments, and even that rate requires paperwork such as Form NR301 to certify US residency. Without it, the bank can default to 25%.
Why the US foreign tax credit may not cancel the Canadian tax
Here's where the second bill comes in. The IRS can treat what your child receives as taxable on their own US return. The standard answer is the foreign tax credit, which lets them claim Canadian tax against US tax on the same income.
That credit only goes so far. It works when your child owes enough US tax to absorb it. In a lower bracket, part of the Canadian tax becomes a sunk cost. Some states don't follow the Canada-US treaty at all, so state tax can apply regardless. And if the inheritance sits in a Canadian account, a US person with foreign accounts above $10,000 USD has FBAR filings to make every year, with steep penalties for missing them. If your child also serves as executor of your Manitoba estate, IRS foreign trust reporting can follow them too.
None of this was visible when the form was signed. The decision was sound for a family that lived in one country.
Three moves to make while you're still drawing the RRIF
The window to fix this is your lifetime, and as a planner holding AMP, SMCP and CCS designations, this is where I spend the most time with families in this position.
Recheck the designation order. If you have a spouse, name them first so the rollover applies, and decide deliberately what reaches your US child afterward and through what route.
Start a slow melt. The minimum withdrawal at age 71 is 5.28%. Drawing more than the minimum in lower-income years, paying Canadian tax at rates you can plan for, shrinks the balance that would otherwise hit one final return. Those funds can be gifted or reinvested in non-registered accounts, which travel across the border far more cleanly. Building non-registered wealth earlier, including through the Smith Manoeuvre™, gives you more of that flexibility.
Price an offset. Permanent life insurance can provide a tax-free benefit sized to cover the tax on the RRIF. Naming a Canadian charity for part of the account produces credits against the final return.
Then look at that beneficiary line again and ask whether it was written for the family you have now.

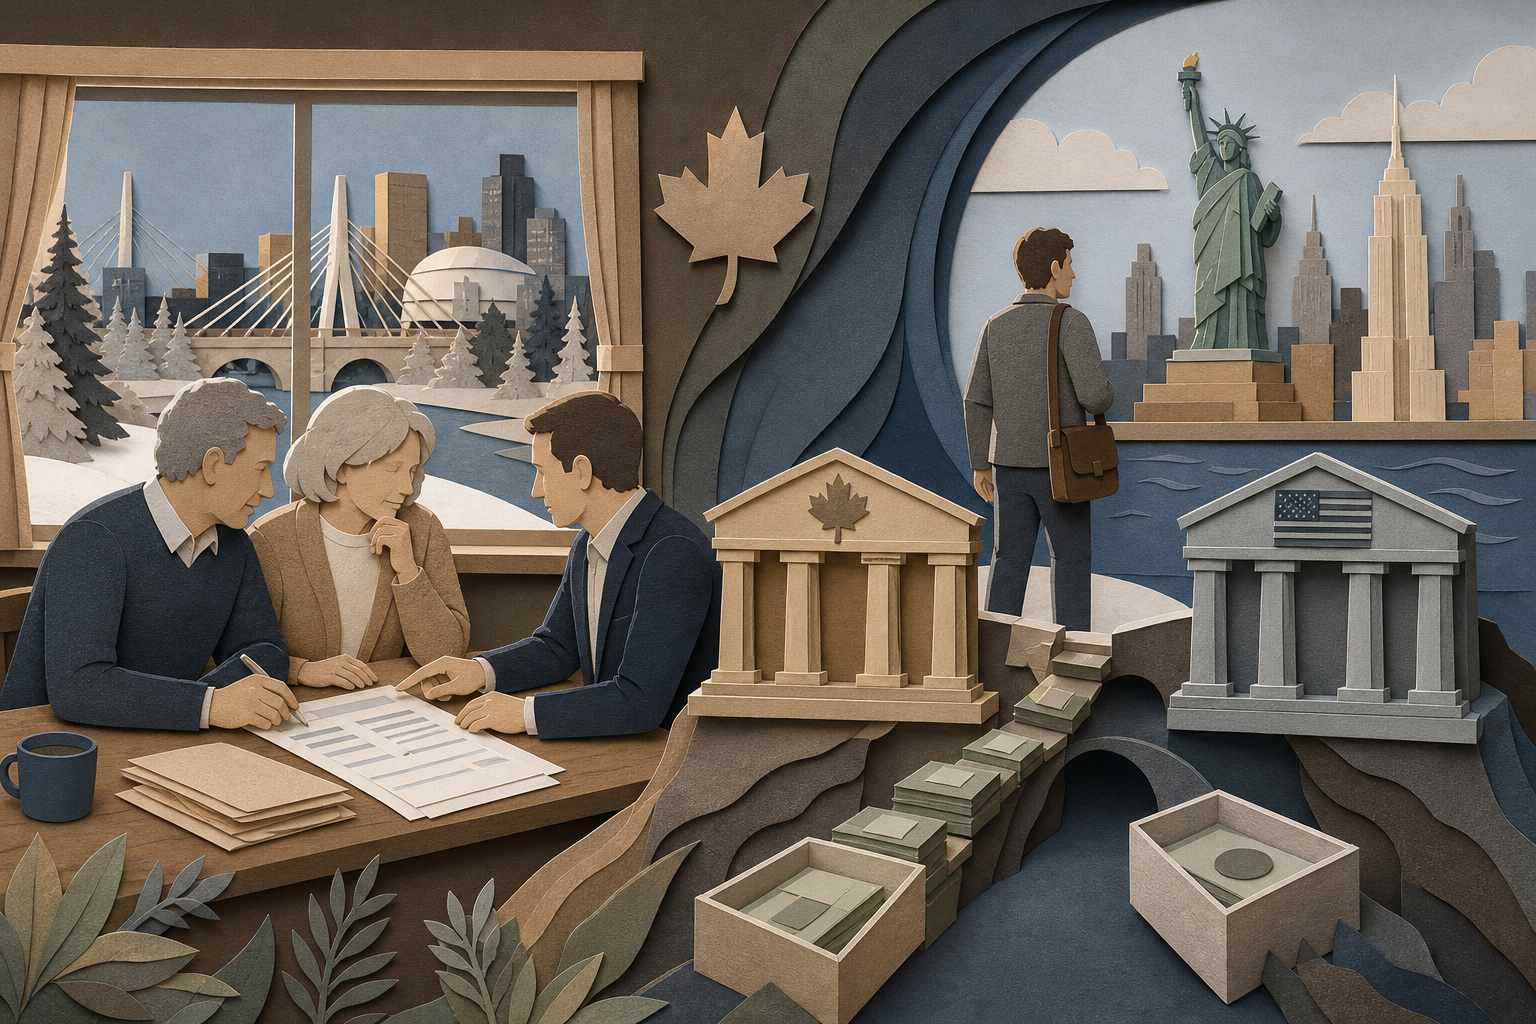
If you have a RRIF and an adult child south of the border, pull out your own designation and look at it. The plan you made assumed one tax system. Your child lives under two, and the money can be taxed by both before it settles in their account. I teach this as one of the quieter estate risks I see, because nothing about it feels risky until the estate is being settled.
Why the RRIF rollover disappears when your child lives in the US
Most people's sense that RRIFs pass smoothly comes from the spousal case. Leave the account to a spouse and Canada lets it roll over, tax-deferred. That rollover is reserved for spouses, so a US-based child, an adult non-spouse, doesn't get it.
When there's no surviving spouse named, typically 100% of the RRIF balance is added to the deceased's final Canadian return. As an illustration, a $500,000 RRIF stacked on top of a year's other income pushes much of it into Manitoba's top bracket. On a lump sum paid to a non-resident, the financial institution may also apply Canada's standard 25% non-resident withholding. The 15% treaty rate is meant for periodic payments, and even that rate requires paperwork such as Form NR301 to certify US residency. Without it, the bank can default to 25%.
Why the US foreign tax credit may not cancel the Canadian tax
Here's where the second bill comes in. The IRS can treat what your child receives as taxable on their own US return. The standard answer is the foreign tax credit, which lets them claim Canadian tax against US tax on the same income.
That credit only goes so far. It works when your child owes enough US tax to absorb it. In a lower bracket, part of the Canadian tax becomes a sunk cost. Some states don't follow the Canada-US treaty at all, so state tax can apply regardless. And if the inheritance sits in a Canadian account, a US person with foreign accounts above $10,000 USD has FBAR filings to make every year, with steep penalties for missing them. If your child also serves as executor of your Manitoba estate, IRS foreign trust reporting can follow them too.
None of this was visible when the form was signed. The decision was sound for a family that lived in one country.
Three moves to make while you're still drawing the RRIF
The window to fix this is your lifetime, and as a planner holding AMP, SMCP and CCS designations, this is where I spend the most time with families in this position.
Then look at that beneficiary line again and ask whether it was written for the family you have now.
Sources
Read Next
Your Diversified Portfolio Has No Defence Against a Tariff Announcement
Selling Your Bond ETF for GICs Swaps Price Swings for Reinvestment Risk
Why the Rate Hike Hits Your Line of Credit Before Your Fixed Mortgage
Stop Betting Your Mortgage on the Bank of Canada's Next Move